What a serious roadmap from here to a post-labor economy would actually have to contain
Elon Musk — Image by aviationa2z.com
Elon Musk has been warning about falling birth rates for the better part of a decade. In 2019 he called population collapse the biggest problem the world would face in twenty years. In 2022 he argued it was a larger risk to civilization than global warming. In April 2025, responding to federal data showing American births at their lowest level since 1979, he posted that low birth rates will end civilization. He has also spent millions funding demographic research, including a ten-million-dollar donation to the University of Texas at Austin that seeded a population research initiative there.
At the same time, he runs companies whose explicit purpose is to make human labor less necessary, and he has said repeatedly that the end state of that work is a world where employment is optional and some form of universal income is mandatory.
The apparent contradiction is obvious enough that it has become a genre of commentary: why demand more workers while building the machines that make workers unnecessary? But the contradiction is narrower than it looks, and understanding exactly where it bites is the beginning of any useful plan.
The pro-natal argument is a claim about the very long run. It says that human beings are the source of novelty, ambition, and direction, that machines extend those capacities rather than replace them, and that a species which stops reproducing eventually stops mattering regardless of how much output it can generate per head. The automation argument is a claim about the short run. It says the marginal cost of cognitive and physical work is collapsing and that the institutions built around wage labor are about to stop functioning.
Both claims can be true. They only conflict in the middle — in the decades between the moment when wages stop working as a distribution mechanism and the moment when something else starts. That middle is where everyone actually lives. And it is the part of the story for which nobody has published a plan.
What follows is an attempt at one: not a wish list of desirable outcomes, but the structure a working bridge would need, judged against what is verifiably happening right now.
What the fertility numbers will and will not support
Start by taking the demography seriously, because it constrains everything downstream.
American fertility is roughly 1.6 births per woman. The general fertility rate hit a record low of 53.1 births per thousand women aged fifteen to forty-four in 2025, according to provisional figures the Centers for Disease Control released in April 2026. Roughly seven hundred thousand fewer babies were born in 2025 than at the 2007 peak. Replacement is about 2.1. So the direction is not in dispute.
What is in dispute is whether policy can change it, and the two best natural experiments both cut against optimism.
South Korea has spent more than two hundred and eighty trillion won — about two hundred and ten billion dollars — over sixteen years on cash grants, parental leave, childcare, and housing help. Its fertility rate bottomed at 0.72 in 2023, the lowest ever recorded anywhere, then rose to 0.75 in 2024 and 0.80 in 2025. That rebound is real, and it is the first sustained rise in years. It is also a movement of eight hundredths of a child, and demographers attribute much of it to a post-pandemic surge in marriages and to a temporary bulge of women in their early thirties rather than to the spending itself.
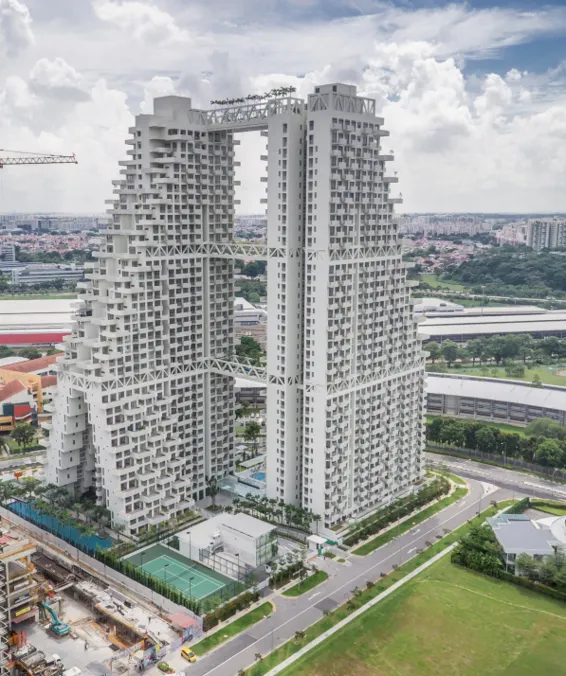
Sky Habitat, Singapore — Image by Safdie Associates
Singapore is the sharper case, because Singapore has already built one piece of the post-scarcity architecture. About eighty percent of its residents live in public housing, roughly ninety percent of households own the home they live in, and homeownership among the poorest tenth of households runs above eighty percent. Housing costs about 3.8 times median income there, against 4.8 in the United States. If material security and affordable housing were the binding constraint on family formation, Singapore should be an outlier in the good direction.
Its total fertility rate fell to 0.87 in 2025, down from 0.97 the year before and from 1.24 a decade earlier. That is the lowest figure the country has ever recorded, on roughly 27,500 resident births. The deputy prime minister told parliament in February 2026 that the citizen population is projected to begin shrinking by the early 2040s, and the government has responded by planning to grant between twenty-five and thirty thousand new citizenships a year and raise permanent residency intake to about forty thousand.
The honest reading is that fertility is not a lever you pull with money. Cost pressure is real and it matters at the margin, but the decline shows up across countries with wildly different housing markets, labor markets, and welfare states. The most consistent driver in the Singaporean and Korean data is not the cost of the second child; it is the collapse in the share of people forming partnerships at all.
This has an uncomfortable implication that cuts against both sides of the original argument. “Have more babies” is not a plan, because nobody knows how to make it happen. But “solve the economy and births will follow” is not a plan either, because the closest thing we have to a solved economy for baseline material needs produced the lowest fertility rate on record. Post-scarcity does not obviously rescue the demographic problem, and the demographic problem does not obviously invalidate post-scarcity. They are separate problems that happen to be argued about by the same people.
What the labor numbers actually show
The displacement is real, measurable, and much narrower than the rhetoric on either side.
Through June 2026, American technology employers announced 139,156 job cuts, up eighty-three percent from the 76,214 announced in the same period of 2025, according to Challenger, Gray and Christmas. Tech accounted for nearly a third of all announced cuts in the country. Artificial intelligence was cited in 101,743 announcements, about twenty-three percent of the total, and it was the single most-cited reason for four consecutive months — a streak with no precedent in the firm’s tracking, which began counting AI as a category in 2023. For scale, AI was cited in 54,836 cuts across the whole of 2025.
Set against that, total announced cuts in the first half of 2026 were 443,604, down forty percent from the same period in 2025, when mass federal workforce reductions inflated the figure. The aggregate labor market is not collapsing. Something more specific is happening.
Researchers at the Stanford Digital Economy Lab, working with payroll records from ADP, found that workers aged twenty-two to twenty-five in the most AI-exposed occupations — software development, customer support — experienced a thirteen percent relative decline in employment following the widespread adoption of generative AI, while employment for older workers in the same occupations remained stable or grew. A later version of the paper, controlling for firm-level shocks, put the figure at sixteen percent. The declines concentrate in occupations where AI substitutes for the work rather than complements it.
The authors have been careful in a way that the coverage of their work usually is not. In a February 2026 update they noted that with the broadest set of controls, the decline in AI-exposed occupations only becomes statistically significant from 2024, and that earlier dips are likely driven by non-AI factors. Their public dashboard measures correlation between exposure and employment trends, not a clean causal link.
So: the entry-level rung is thinning, the effect is real enough to show up in payroll data, and the mechanism is not yet fully pinned down.
Meanwhile the Bureau of Labor Statistics projects the American economy will add 5.2 million jobs between 2024 and 2034, growth of 3.1 percent, against thirteen percent over the prior decade. Health care and social assistance is the fastest-growing sector, adding about two million jobs. The occupation projected to add more jobs than any of the 832 the agency tracks is home health and personal care aides, at roughly 740,000 additional positions. The median annual wage for that occupation in 2024 was $34,900.
That is the actual shape of the transition. Not mass unemployment, but a reallocation: high-wage entry-level cognitive work contracting, low-wage in-person care work expanding, and the ladder between them missing several rungs.
The distributional consequence is already visible in spending. Moody’s Analytics estimates that households in the top twenty percent by income — those above roughly $175,000 a year — accounted for close to sixty percent of personal outlays in the first quarter of 2026, and that their spending rose 6.5 percent over the prior year while the bottom eighty percent managed 2.6 percent, below inflation. Mark Zandi, who produces the estimate, has acknowledged that the methodology has been criticized and may overstate the case, and a Federal Reserve Bank of Minneapolis review published in 2026 found that competing measures range from a steep divergence to almost none. The direction is not seriously contested even if the magnitude is.
The tax base is the labor base
Here is the fact that turns a social problem into a fiscal one, and it is the single most important number in this entire discussion.
Of the $5.26 trillion the United States federal government collected in fiscal year 2025, about 50.5 percent came from individual income taxes and about 33.6 percent from payroll taxes. Corporate income tax contributed $453 billion, under nine percent, and fell fifteen percent year over year. More than four fifths of federal revenue is levied on wages.
Every job that automation eliminates therefore does two things at once: it removes a taxpayer and it adds a claimant. The state’s capacity to respond to displacement shrinks in direct proportion to the displacement itself. There is no version of this where a government waits, observes the damage, and then funds a response, because the funding mechanism is the thing being damaged.
This is why “we’ll figure out redistribution when we need it” is not a neutral position. It is a bet that the revenue base will still be there when the political will arrives.
It is also why the sequencing of any real bridge is the opposite of the usual telling. The usual telling starts with universal basic income. A working bridge starts with revenue.
Four questions a bridge has to answer
Most published visions of the post-labor economy are lists of destinations: universal services, public compute, sovereign wealth funds, shorter weeks. Destinations are not bridges. A bridge is a financing mechanism, a sequence, a trigger, and a failure test. Any plan that cannot answer the following four questions is a description of somewhere else, not a route.
The first is fiscal. What replaces a tax base levied on wages, and does the replacement grow as automation grows? A revenue source that shrinks alongside employment is not a bridge; it is the same cliff with extra steps.
The second is proprietary. Who owns the productive capital, and through what institution do ordinary people hold a claim on it? “The wealth should be shared” is not an answer. A specific legal instrument with a specific governance structure is an answer.
The third is physical. Are the inputs actually getting cheaper? The entire abundance thesis rests on the marginal cost of energy, compute, materials, and construction falling toward zero. If they are rising instead, everything downstream is fantasy.
The fourth is procedural. What is the trigger that starts each phase, and what is the observation that would prove the plan is failing? A roadmap with no failure condition is a mood.
The first girder: making the buildout pay its own way
Take the physical question first, because it is the one where the conventional story is most clearly wrong right now.
Electricity is not getting cheaper in the places where the AI buildout is happening. Wholesale power across the PJM grid, which serves about sixty-five million people across thirteen states and the District of Columbia, averaged $136.53 per megawatt-hour in the first quarter of 2026, up from $77.78 in the same quarter of 2025 — a seventy-six percent increase. Monitoring Analytics, the grid’s independent market monitor, attributed sixty-three percent of the increase to data center load, translating to roughly $9.3 billion in costs recovered from customers. Capacity prices, which secure resources for future peak demand, rose from $28.92 per megawatt-day for the 2024–25 delivery year to $329.17 for 2026–27. Residential electricity costs across the country rose more than six percent over the year to May 2026, faster than the average for other goods. The Natural Resources Defense Council estimates that unconstrained data center growth could add roughly seventy dollars a month to an average family’s bill by 2028.
So the first structural move on the bridge is not a dividend. It is cost allocation: making the automation buildout carry its own infrastructure costs instead of socializing them onto households through the utility bill.
This is not hypothetical. Oregon passed House Bill 3546, the Protecting Oregonians With Energy Responsibility Act, in June 2025. It directs utilities to create a separate rate class for data centers and cryptocurrency operations drawing more than twenty megawatts, with rates that reflect the full cost of serving them and long-term contracts that address stranded-asset risk. The state’s Public Utility Commission approved Portland General Electric’s implementing tariff in May 2026, effective the following month. Large customers in the class pay the full cost of the distribution upgrades their projects require, minimum demand charges of ninety percent of contracted capacity whether they use it or not, and contracts running ten years or longer. Above one hundred megawatts there is a surcharge of one cent per kilowatt-hour that funds energy-efficiency work and bill assistance for low-income households.
The measured result, by the utility’s own estimate: data center rates up about twenty-nine percent, residential rates down 1.3 percent, small business rates down 3.7 percent. Roughly sixteen facilities were affected immediately. Twenty-three states have now adopted some version of a dedicated large-load framework.
That is what a girder looks like. It is small, it is specific, it is already load-bearing, and it establishes the principle the entire bridge depends on: that the beneficiaries of automation pay the costs of automation, at the point where those costs are incurred, by statute rather than by goodwill.
The second girder: ownership, and the governance that has to come with it
The proprietary question has two working models, one good and one cautionary, and the United States has recently started building a third without deciding which it wants to be.
Norway’s Government Pension Fund Global was established in 1990 on the premise that petroleum wealth was finite and belonged to future generations. Every krone of government petroleum revenue flows into it, it invests exclusively abroad, and a fiscal rule limits annual government withdrawals to roughly three percent of its value — the estimated long-term real return. By the end of 2025 it held about 21.3 trillion Norwegian kroner, roughly two trillion dollars, spread across some seven thousand companies and amounting to about 1.5 percent of the value of all listed equity on the planet. Per citizen, the notional claim is somewhere near four hundred thousand dollars. Nobody can withdraw it. It is a claim on a collective asset, and the discipline that makes it work is the spending rule, not the size.
Alaska is the cautionary version. The Permanent Fund holds about eighty-three billion dollars and supplies between half and sixty percent of the state’s general-purpose revenue. Since 1982 a portion of its earnings has been paid out as an annual dividend to residents. The 2025 dividend was one thousand dollars, paid to more than six hundred thousand people. The dividend was set by statutory formula until 2016, when the legislature, facing budget shortfalls, began setting it by annual political negotiation instead. The formula remains in law. Lawmakers are simply not obliged to follow it, and they have not.
That is the failure mode for every proposal in this space, and it is a design failure rather than a moral one. An income floor that depends on an annual vote is not a floor. It is a subsidy with the political stability of a subsidy, which is to say it is largest in election years.
The third model is being assembled right now with no evident design at all. Since January 2025 the United States government has announced roughly $26.7 billion of investments across thirty deals involving direct ownership, according to the Council on Foreign Relations tracker. The largest is a 9.9 percent stake in Intel, acquired in August 2025 for about $8.9 billion in CHIPS Act and Defense Department funds, and recently valued near forty-two billion dollars. Others include four hundred million dollars in the rare-earth producer MP Materials, a golden share retained in the sale of U.S. Steel, and a set of positions in quantum computing firms. The White House has described the Intel stake as something like a down payment on a sovereign wealth fund.
The instructive comparison is to the last time the federal government held corporate equity at scale. The Troubled Asset Relief Program came with a statutory special inspector general filing quarterly reports to Congress, a congressional oversight panel, and standing accountability office audits — and even that apparatus was judged inadequate at the time. The current portfolio has none of it.
So the design requirements for this girder are not exotic. A public stake in automated capital needs three things that the Norwegian fund has and the American portfolio does not: a spending rule with constitutional or statutory force that cannot be suspended by an ordinary budget vote, a firewall between the fund’s investment decisions and the sitting administration’s political interests, and a disclosure regime that reports holdings and returns on a fixed schedule to a body with subpoena power. Without those, public ownership of AI infrastructure is not a bridge to shared abundance. It is a new patronage system with better public relations.
The third girder: what a floor can and cannot do
The best evidence available on unconditional cash comes from a randomized controlled trial run through OpenResearch in Illinois and Texas, in which a thousand low-income adults received one thousand dollars a month for three years while two thousand controls received fifty dollars a month. It is the most comprehensive study of its kind conducted in the United States, and its results are more useful for being mixed.
Recipients reduced their work by roughly one to two hours a week. Labor-force participation fell by a few percentage points. Total individual income excluding the transfer dropped by around eighteen hundred dollars a year relative to the control group. Of all the categories of time use the researchers measured, the largest increase was leisure. Despite detailed questioning about job amenities, the researchers found no improvement in the quality of employment, and their confidence intervals were tight enough to rule out even small improvements — the expected mechanism, where a cushion lets people search longer and land better work, did not appear.
On the other side of the ledger, recipients reported better financial health and greater ability to absorb a shock. They were more likely to move neighborhoods. Follow-up analyses published in 2025 found clear improvements in parenting: more spending on children, closer supervision, more consistent discipline, and, in the interview data, parents who were more emotionally present. Effects were largest among the lowest-income and single-parent households. Attitudes toward the importance of work did not decline.
The correct conclusion is narrow and worth stating plainly. A cash floor buys stability, agency, and better conditions for children. It does not, by itself, buy mobility. It does not produce a better job or a higher wage. It reduces work modestly and the reduction goes to rest rather than to advancement.
This matters enormously for how a floor is placed in the sequence. A floor deployed on its own, as the primary response to displacement, produces a population that is materially secure and structurally static — which is precisely the outcome critics of universal income predict and precisely the outcome its advocates say they do not want. A floor deployed alongside subsidized capability-building and an ownership stake is a different instrument, because the stability it provides is what makes a training program or a business attempt survivable.
The trigger question also resolves here. A floor that arrives after displacement is a rescue, arrives late, and is fought over. A floor indexed to a measured indicator — the ratio of entry-level hiring to labor force entrants, say, or the share of national income accruing to labor — scales up automatically as the thing it exists to offset gets worse, and requires no act of political courage at the moment when courage is scarcest.
The fourth girder: rebuilding the base
Which returns to the fiscal question, the hardest of the four, because it is the one where nobody has a working example.
The theory is straightforward. If four fifths of revenue is levied on wages and wages are shrinking as a share of national income, the base has to shift toward the things that are growing: capital income, land values, compute, energy, and physical resource throughput. Land value taxation has the strongest theoretical support of any of these, since it falls on a supply that cannot flee and captures exactly the positional scarcity that automation cannot relieve.
The practice is where it falls apart. The world’s only real attempt at taxing automation directly was South Korea’s, in 2017 and 2018 — widely reported as the first robot tax, though what it actually did was reduce an existing corporate tax deduction for automation investment, worth three to seven percent, by up to two percentage points. That is a subsidy reduction rather than a tax, and its effects were correspondingly modest. Defining the taxable unit is the recurring problem: a robot is identifiable, but the software agent that eliminates a hundred jobs from a spreadsheet is not, and a tax that only catches the visible machines simply pushes displacement toward the invisible ones.
Taxing compute is the more tractable version, because compute is metered, physically located, and already billed. It has the useful property of scaling directly with the thing it is meant to offset. It has the obvious problem of being trivially relocatable across borders, which makes it a coordination problem rather than a national one — and coordination problems of this kind have historically been solved late or not at all.
The honest position is that no country has demonstrated a revenue base that grows with automation. This is the weakest span on the bridge, and any plan that glosses it is not a serious plan.
The far side, and what stays scarce
Assume all of that gets built. What does the other side actually look like?
Abundance is category-specific, and the categories divide cleanly.
Things that can be copied become nearly free: software, designs, diagnosis, tutoring, legal and medical first-line advice, entertainment. Things that can be manufactured by automated processes from common inputs become cheap: standard food, standard goods, standard modular housing, standard transport. This is the genuine content of the post-scarcity claim and it is substantial. Universal baseline security — nobody involuntarily hungry, homeless, or without care — is a real technical possibility rather than a utopian one.
Things that cannot be copied do not become free, and several become more expensive precisely because everything else got cheap.
Land is the clearest case. The structure on a lot can be automated toward the cost of its materials. The lot cannot. Everyone can have a well-built home; not everyone can have one in a specific desirable place, and no amount of robotics changes that. Positional goods generally — prime locations, physical presence at scarce events, original artifacts — remain rationed by something, and the only question is whether that something is price, lottery, tenure, or queue.
Physical resources remain bounded. Copper, lithium, rare earth elements, fresh water, and arable land have extraction limits and ecological costs that recycling reduces but does not eliminate.
Energy and its waste heat remain bounded, and, as the current data show, are the immediate binding constraint rather than a distant one.
Human attention, presence, and provenance remain scarce by definition, and their price rises as synthetic alternatives proliferate. This is the mechanism by which a post-labor economy still has an upper tier: what people pay premiums for is precisely what cannot be produced at scale.
The two-tier structure that results is not a compromise between capitalism and something else. It is what falls out of the physics. A guaranteed floor of copyable and manufacturable goods, and an open market above it for everything that remains genuinely scarce, in which ambition, enterprise, and risk still produce differential outcomes. The person who wants to build a business, take on risk, and end up better off than the baseline can still do all of that. The difference is that failure returns them to the floor rather than to destitution, which — on the evidence from the cash transfer trial — is a condition under which people take more entrepreneurial risk, not less.
Whether it is desirable
Three objections deserve more weight than they usually get.
The first is meaning. Work supplies structure, identity, and social role, and a floor supplies none of these. The cash transfer evidence is suggestive here: recipients did not devalue work, but the time they freed up went to leisure rather than to advancement or civic participation. Whatever replaces the organizing function of employment has to be built deliberately, and nobody has demonstrated a scalable version.
The second is political leverage, and it is the most serious. Labor’s historical bargaining power came from the ability to withdraw. Strikes worked because production stopped. A population whose income arrives as a dividend has no equivalent instrument. Withholding participation from an economy that does not require your participation achieves nothing. The only remaining leverage is the vote, which means that the governance design of the fund — its insulation, its audit regime, its spending rule — is not an implementation detail. It is the entire substance of the arrangement. Alaska’s ignored formula is what happens when that design is weak, and Alaska is a wealthy state with strong institutions and a single, simple, visible revenue source.
The third is that abundance does not appear to solve the problem that started this. Singapore is as close as any country has come to guaranteeing material housing security, and its fertility rate is the lowest ever recorded. If the hope embedded in the accelerationist position is that post-scarcity will make family formation easy again, the closest available evidence does not support it. The demographic question survives the economic one intact, and will need its own answer.
Positioning on the upper arm of the K
For those currently on the favorable side, the structural advice is simple and the vulnerability is specific.
The simple part: convert wage income into claims. If capital captures the returns to automation, the only durable protection is to hold capital. This is not a market-timing argument; it is an observation that the ratio of your capital income to your wage income is the single variable that determines which arm of the K you are on ten years from now.
Beyond that, the defensible positions in a professional services economy shift from execution to accountability. Models produce the draft, the analysis, the code, the design. What they cannot do is bear legal or professional responsibility for the result. Businesses that sell verification, compliance, indemnification, and signature — where a named human entity carries the risk — retain pricing power that businesses selling output do not. The same logic favors regulated and physical domains: licensed trades, energy infrastructure, specialized engineering, anything where the constraint is a permit, a site visit, or a certification rather than a token budget.
The specific vulnerability is worth stating clearly, because it is under-discussed. The upper arm’s position is portfolio-dependent. Moody’s own framing of the K-shaped economy is that it leaves aggregate consumption resting on a narrow group whose spending tracks how their holdings are performing. That group’s holdings are heavily weighted toward the same AI capital expenditure cycle that produced their advantage. A correction in that cycle hits their consumption, their employment, and their asset values simultaneously and in the same direction. The hedge is not more exposure to the winning trade; it is uncorrelated income, low fixed obligations, and liquidity — the same advice that applies below, arrived at from the opposite direction.
Positioning on the lower arm
For those who cannot wait for policy, the moves that matter are the ones that increase optionality per dollar.
Fixed obligations are the binding constraint. A household with low fixed monthly commitments can absorb a job loss, accept a lower-paid but more durable role, retrain, relocate, or start something. A household with high fixed commitments tied to an automatable wage has none of those options regardless of income. Reducing recurring obligations is worth more than an equivalent increase in earnings, because it converts a dependency into a choice. Hardship programs, forbearance, and rate reductions are worth pursuing before reserves are gone rather than after, and the same is true of local assistance programs, which are easier to enter from a position of partial stability than from crisis.
On work, the evidence points in a direction that is genuinely helpful and also genuinely uncomfortable. The occupations projected to add the most jobs over the next decade are in direct care, and they are poorly paid — a median of $34,900 in 2024 for home health and personal care aides. That is simultaneously the clearest available signal about where human labor remains necessary and a reminder that necessity does not set wages. The versions of this work that pay are the credentialed ones: nurse practitioners, physician assistants, therapists and their assistants, behavioral health specialists, all projected to grow several times faster than the economy-wide average. The licensed physical trades occupy the same structural position from the other direction. In both cases the moat is a certification and a physical presence, not a skill that a model lacks.
The general principle underneath both arms of the K is the same, which is why it is worth naming: the durable move is to convert flow into claim. Wages are flow. Equity, land, licenses, certifications, and relationships are claims. Flow is what automation compresses. Claims are what it bids up. Everyone whose income is currently a flow is on the same side of that trade regardless of its size.
Free and cheap AI tools are worth using aggressively in the meantime, and specifically for the administrative work that used to require paying a professional: drafting a hardship letter to a creditor, navigating benefits paperwork, preparing for a negotiation, learning the fundamentals of a trade. The asymmetry there runs in the individual’s favor for the moment, because these tools reduce the cost of the things that used to keep people locked out of processes designed to be exhausting.
What would show the bridge is being built
A roadmap with no failure test is a mood, so here are five observable things that would distinguish a bridge under construction from a slogan.
Whether the cost-allocation frameworks spreading through state utility commissions hold up when they are challenged, and whether they extend from electricity to water, land, and transmission. Twenty-three states have adopted large-load frameworks; the question is whether they survive contact with the money.
Whether any public equity stake in AI infrastructure acquires a statutory spending rule and an independent audit regime, or whether the current portfolio stays undocumented. The gap between the Norwegian design and the current American practice is the whole difference between a national endowment and a slush fund.
Whether the share of federal revenue drawn from wages begins to fall as a matter of policy rather than as a symptom of decline. A shrinking wage share of revenue with no offsetting base is the failure signature.
Whether entry-level hiring recovers relative to labor force entrants, or whether the Stanford cohort effect persists and widens. This is the leading indicator, and it is now published on a rolling basis.
And whether any income floor anywhere is indexed to a measured displacement variable rather than set by annual appropriation. That single design choice determines whether the floor exists during the crisis it was built for.
None of this requires believing in a particular future. It requires only noticing that the transition, however it resolves, is being financed out of a tax base that automation erodes, distributed through a wage mechanism that automation breaks, and governed by institutions that have not yet been asked to hold a claim on capital in trust for anyone.
The birth-rate argument and the automation argument are both, at bottom, bets that this middle period will be short. The plan is what you need if it is long.